Issue 111 – Back the winners
A Trump crypto adviser’s firm took millions from Tether while he shaped stablecoin rules in their favor, a Senate probe targets Commerce Secretary Lutnick’s not-so-former firm, and crypto’s biggest super PAC plays it safe

The crypto industry’s flagship super PAC, Fairshake, has announced the House candidates it plans to back in the midterms. All 32 are incumbents, and all but four are in safe seats, which makes for a convenient way to pad a win rate and then claim it proves the existence of a crypto voter bloc. Rather than fighting for competitive seats, the PAC has abandoned several reliable allies in tough races. It seems more focused on rewarding high-ranking allies, such as Financial Services Committee chair French Hill and Bryan Steil, who chairs the House’s digital assets subcommittee.
Meanwhile, the revolving door between Trump’s White House and the crypto industry is spinning so fast it’s threatening to fly off its hinges. Patrick Witt, the latest executive director of Trump’s crypto council, has left for an as-yet-unnamed job in the private sector, leaving the council without a director or deputy, and the crypto industry wondering whether the White House has lost interest. New reporting from the Wall Street Journal outlines how stablecoin giant Tether cultivated a lucrative business relationship with his predecessor, Bo Hines, while Hines negotiated the Genius Act stablecoin law. Tether paid millions to Hines’ family consulting firm, then hired him to run its US arm after he stepped down from his advisory role. Tether’s other friends in high places are drawing scrutiny too: a Senate subcommittee is probing the stablecoin issuer’s ties to Cantor Fitzgerald, the firm Commerce Secretary Howard Lutnick supposedly divested from by handing it to his sons.
In the White House
Tether, Bo Hines, and NXUM
Bo Hines, President Trump’s bizarre choice [I72] to serve as the first executive director of his crypto advisory council, was among the key architects of the Genius Act, the stablecoin law signed in July 2025. Hines’ previous qualifications consisted of playing college football, losing two Congressional races, and co-owning a small consulting firm called NXUM with his father. He kept his stake in NXUM when he joined the administration.
The Wall Street Journal has now reported that weeks after Hines began working on the bill, his father and their fellow NXUM co-owner Gary Dennis met with Tether CEO Paolo Ardoino. Tether is the largest stablecoin issuer, and had the most riding on the legislation. Though NXUM previously had little involvement with the crypto sector, it pitched Tether on a “strategic lobbying” and PR campaign that has netted NXUM at least $6.3 million to date, with payments that began while Hines was still at the White House and were split three ways among the co-owners. The final deal omitted any mention of lobbying, and was routed through a separate marketing firm.
Meanwhile, Hines pushed legislators to double the grace period for crypto exchanges to stop offering noncompliant stablecoins — a change that primarily benefited Tether. He also remained active in Signal chats with his NXUM partners. When some Republican congresspeople stalled the bill, his father informed Dennis he’d gotten a “very worried” call from Ardoino and that Tether wanted them to “obliterate” the holdouts. Hours later, Hines sent the NXUM group chat talking points casting the legislators as “undermining the president and ... bought and paid for by democratic shills like coinbase and a16z”. When Trump brokered a deal with the holdouts weeks later, Dennis bragged to an associate, “Bo got it done.” Three weeks after the bill was signed, Hines left the White House; the following month, he was named CEO of Tether’s new US arm.
NXUM has only grown more entangled with Tether since. The consulting firm, which is pitching investors on a deal in which Tether would buy a 25% stake for $56 million, has started branding itself as the “strategic media infrastructure layer behind Tether”. It also helped launch the Fellowship PAC, which is chaired by Jesse Spiro, Tether US’s head of government affairs [Tether PAC]. The PAC is funded almost entirely by Cantor Fitzgerald, an investor in Tether and its primary US financial partner, which was previously run by now-Commerce Secretary Howard Lutnick. The PAC has paid NXUM more than $6.5 million. Before it launched, Dennis reminded an associate: “Again, no link to Tether, Nxum, Bo”.
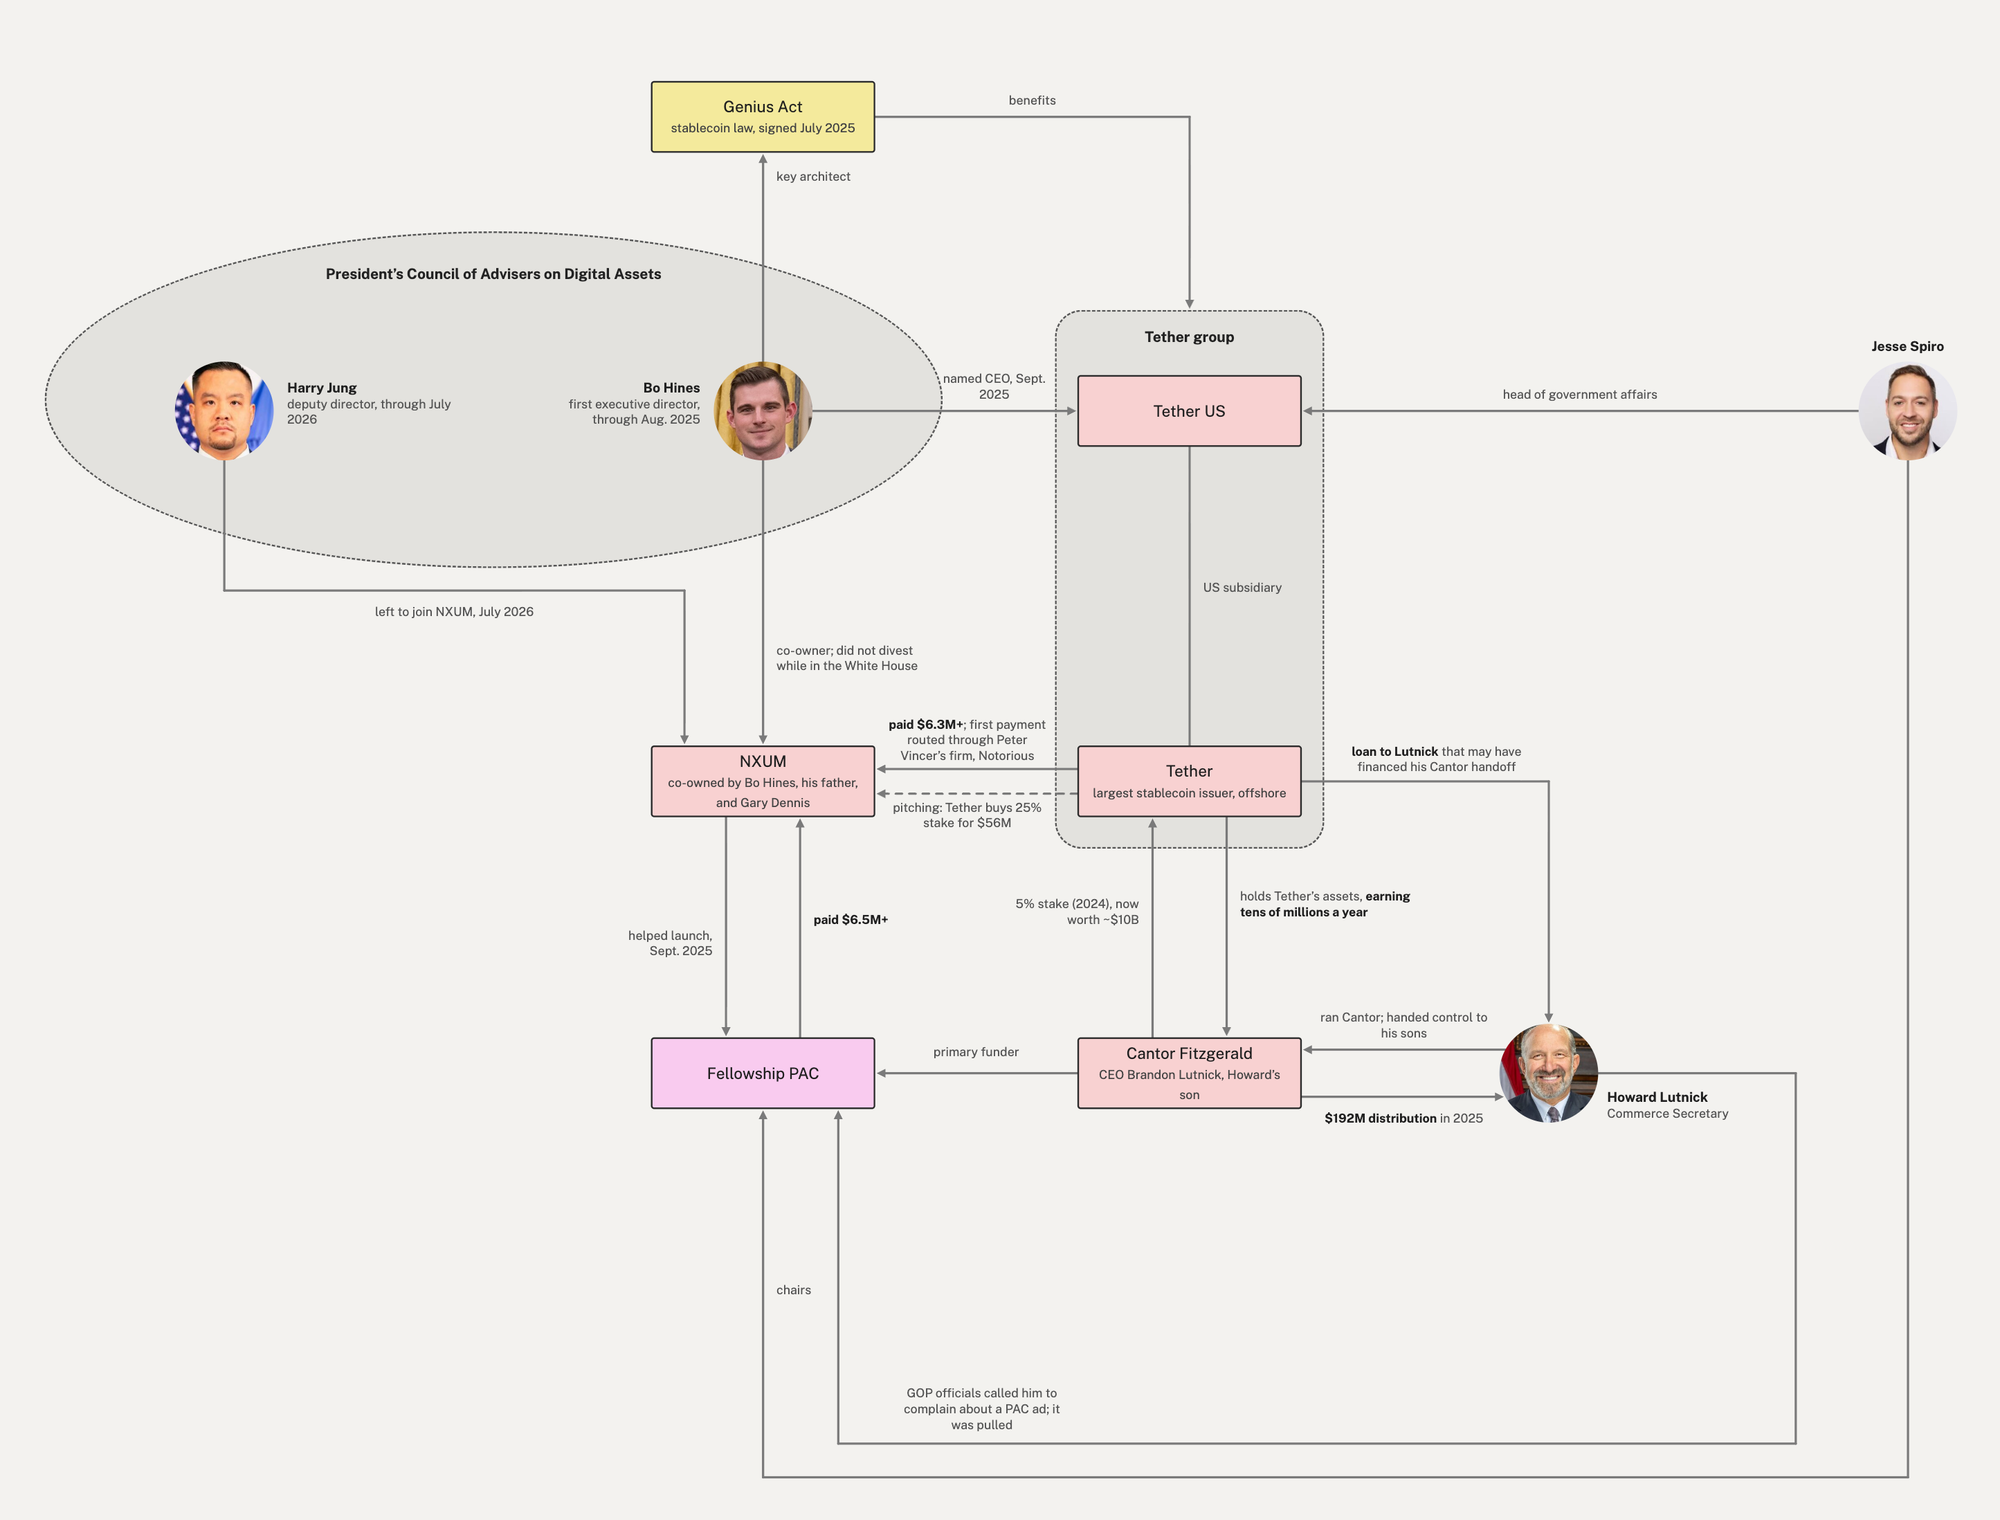
Hines was succeeded on the crypto council by Patrick Witt, whose resume likewise featured college football and failed congressional bids [I90]. Witt took over negotiations on the Clarity Act crypto market structure bill, which recently fizzled after falling short of the votes needed for cloture [I110]. In July, the council’s deputy director, Harry Jung, stepped down to join (you guessed it!) NXUM.1 Now, Witt has left his post, presumably to collect his reward. I look forward to learning who’s paying it.
His departure adds to growing nerves in the crypto sector that the White House is losing interest. David Sacks stepped down from his combined “AI and crypto czar” role in March, and earlier this month Trump tapped Jay Clayton to become his AI czar.2 No crypto czar has been named, and the digital assets advisory council is now without a director or deputy director. The Clarity Act is dead, with little hope of being revived after the midterms. If I were among the crypto executives whose money has fueled more than $250 million in super PAC election spending since 2024, I might also be a little worried that the administration got what it needed from me and is now moving on to newer, shinier things.3
Tether, Howard Lutnick, and Cantor Fitzgerald
Hines isn’t the only Trump official whose ties to Tether are drawing scrutiny. The Senate Permanent Subcommittee on Investigations is probing the relationship between the stablecoin firm and financial giant Cantor Fitzgerald, which was previously headed by Commerce Secretary Howard Lutnick. Upon his cabinet appointment, Lutnick claimed to have satisfied his ethics requirements by transferring his interest in the firm to a trust benefiting his four children, and handing control to two of his sons — a move borrowed from Trump. Like Trump, Lutnick has continued to profit from the family business — his 2025 financial disclosure reported a $192 million distribution from the firm. Nor does he seem to have stepped away from it: in April, when the Cantor-funded Fellowship PAC disclosed plans to spend $1.75 million backing Ken Paxton in the Texas Senate primary runoff, senior Republican officials called Lutnick to complain. The PAC quietly dropped the ad three days later [I105].
An October 8 letter from PSI Ranking Member Richard Blumenthal to Cantor Chairman and CEO Brandon Lutnick disclosed that the subcommittee is investigating Cantor Fitzgerald’s relationship with Tether and its connections to the Trump regime.4 Cantor took a 5% stake in the stablecoin issuer in 2024, and according to Blumenthal, “Since the President’s return to office, Cantor Fitzgerald’s five percent stake in Tether has increased in value from $600 million to an estimated $10 billion, in addition to the tens of millions of dollars the company collects every year from the assets it holds for Tether.” The letter raises concerns about Tether’s use by illicit actors, including Iran’s shadow banking system, and about Cantor’s close ties to Lutnick and the rest of the Trump administration.
Blumenthal requested information on Cantor Fitzgerald’s due diligence on Tether’s reserves and anti-money laundering programs, the terms of a loan from Tether to Howard Lutnick that may have financed his transfer of the business to his children [I103], and copies of any communications by Secretary Lutnick involving regulatory matters or with other White House advisors.4
In regulators
The Independent Community Bankers of America has sued the Office of the Comptroller of the Currency over its recent rulemaking and its spree of national trust bank charters. At least 13 of the 21 charters granted by the OCC under Trump have gone to crypto firms, including Circle, Ripple, and the Trump family’s own World Liberty Financial [I88, 98, 99, 101, 102, 107]. While the national trust bank framework is intended to let firms hold assets on clients’ behalf without the more stringent oversight applied to traditional banks that take deposits and lend them out, the community banks argue that the OCC has overstepped its authority and turned the regime into a backdoor for crypto companies to get the perks of a bank charter without the rules. The suit singles out Protego, which won conditional approval for a trust charter despite plans to offer crypto custody, trading, lending, and asset management services.
The OCC’s expansion “creates a gaping hole in regulation,” the trade group writes, letting crypto firms perform many of the same functions as community banks “while evading the fundamental safeguards, obligations, and oversight of those banks.” Their customers don’t receive the protections of deposit insurance, the separation of banking and commerce, or limits on dealings with risky investments like hedge funds. And because the national charters preempt state law, they lose some state consumer protections. Many won’t realize it: “Customers will reasonably assume that a company having ‘national bank’ in its title is an insured depository institution.”
There’s also very little precedent for what will happen if one of these firms fails. “The OCC has not managed an uninsured bank receivership in nearly one hundred years,” the lawsuit points out, warning that “failures of risky uninsured national trust banks could spread instability throughout the nation’s financial system, including by spreading contagion risks to other traditional banks like community banks.”
The suit also echoes some of the same arguments raised by community banks during the Clarity Act negotiations: that crypto firms, freed from much of the regulatory burden banks carry, will siphon deposits away from community banks and reduce their capacity to lend [I91, 99, 107, 108, 110].
ICBA President and CEO Rebeca Romero Rainey said in a statement that “Congress did not create the national trust charter as a side door into the banking system for crypto firms seeking the credibility of a federal bank charter.” But crypto firms have previously balked at complaints from traditional banks. Last spring, Coinbase’s then-Chief Legal Officer Paul Grewal accused the ICBA of protectionism, writing, “Imagine opposing a regulated trust charter because you prefer crypto to stay … unregulated” [I96, 102].a
In elections and political influence
The crypto industry’s flagship super PAC, Fairshake, has announced a list of 32 House candidates it plans to back in the midterms. All of them are incumbents; 13 are Democrats, and 19 are Republicans. All but four are in races dubbed “safe” for them by the Cook Political Report.5
PAC spokesperson Geoff Vetter gave the game away when he bragged to The Hill, “We’ve won 53 of the 57 races we engaged in this cycle”.6 As I’ve noted previously [I68, 70, 108], the crypto PACs and advocacy groups often support shoo-in candidates so that they can later claim that their win rate reflects some silent majority of Americans who support the “crypto agenda”. Similarly, when Coinbase-linked Stand With Crypto endorsed 39 candidates in 2024, The Hill estimated prior to Election Day that 32 of them had a 75% or higher chance of winning [I68].
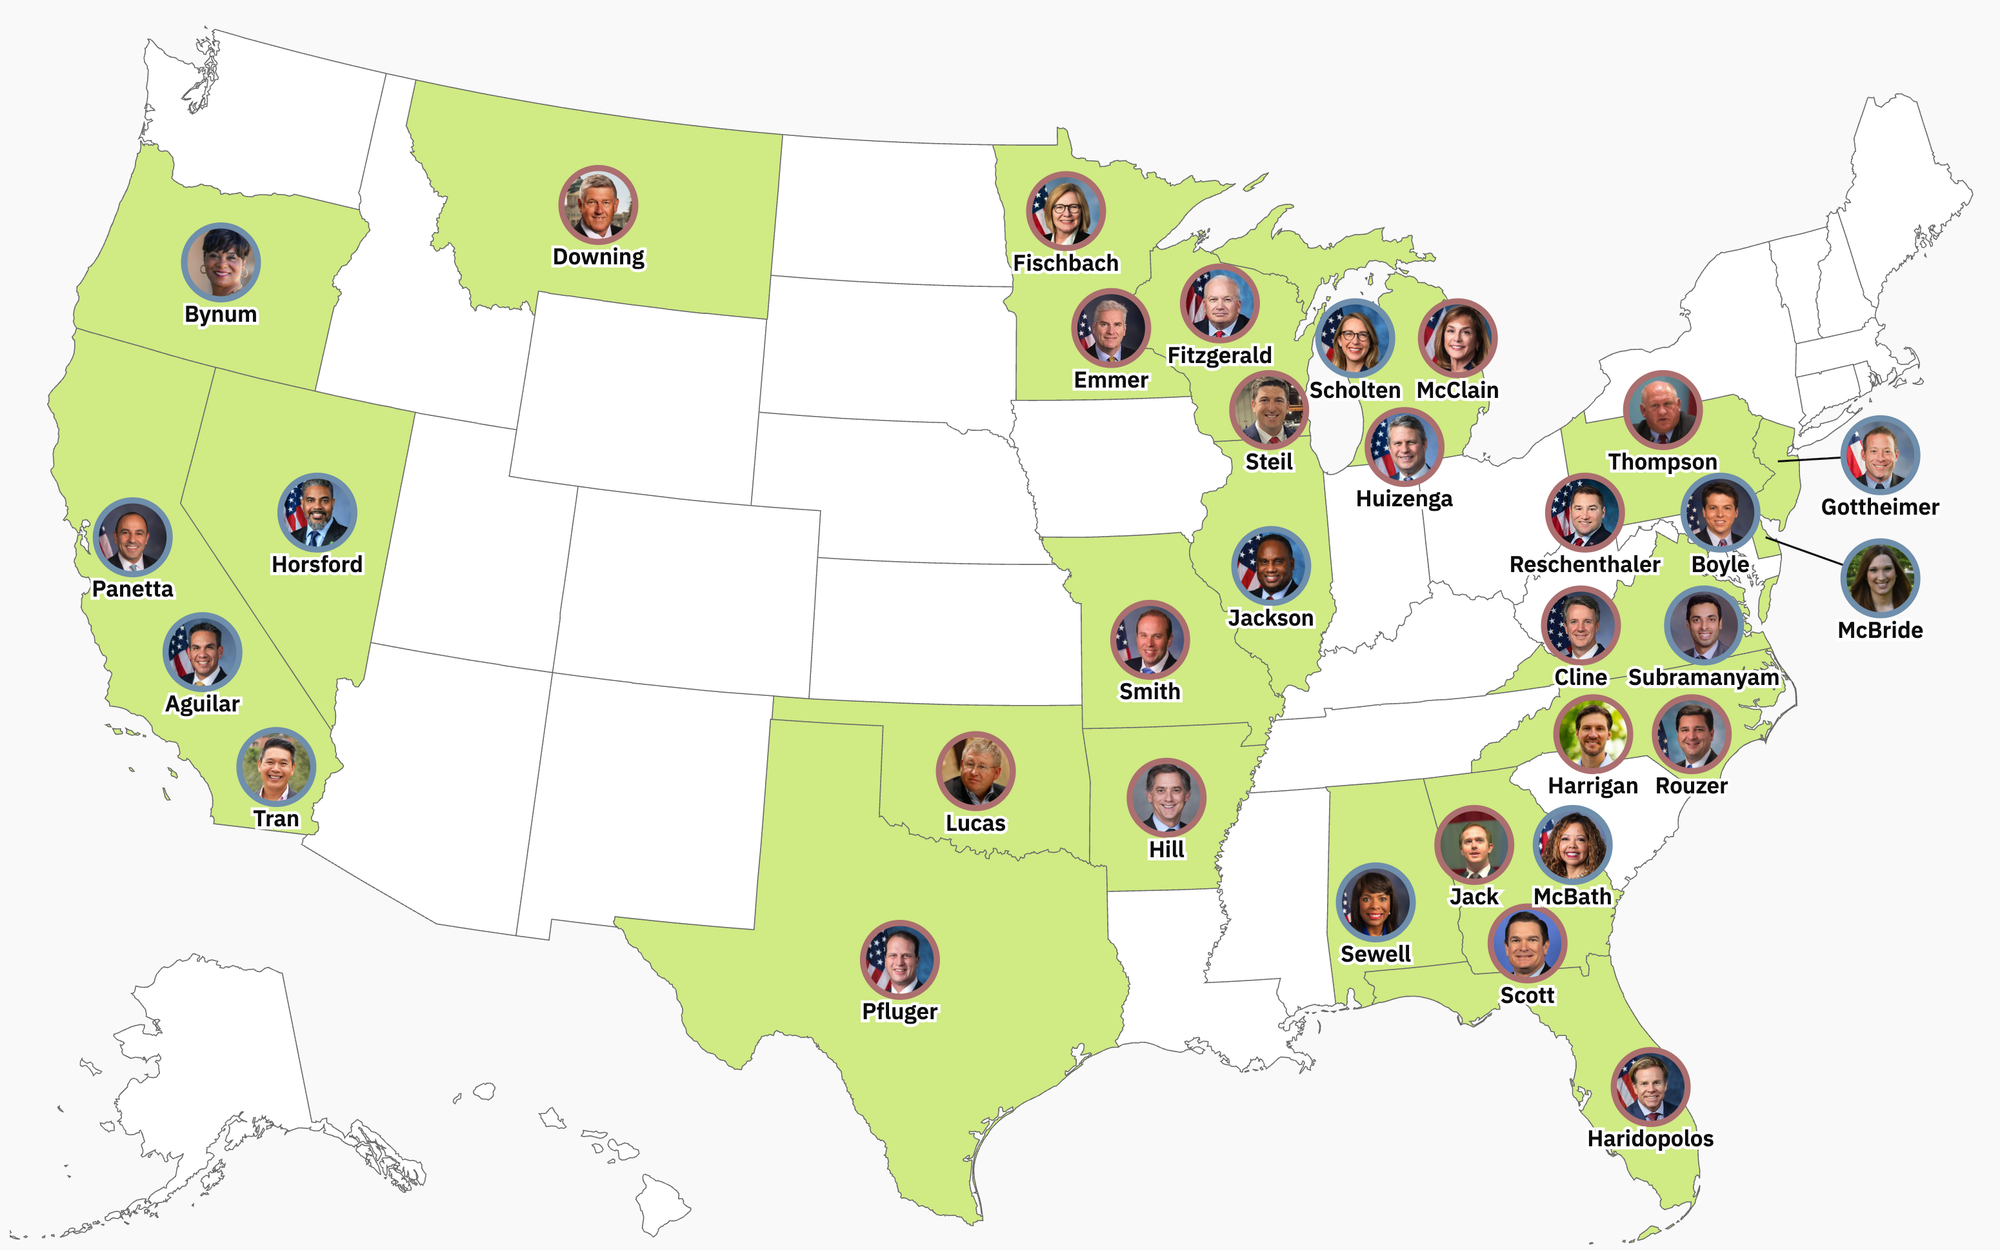
Out of their list, the Fairshake network has so far spent the most on Republicans Bill Huizenga (MI, $1.5 million) and French Hill (AR, $1.4 million). It has spent around $1 million apiece supporting Bryan Steil (R-WI), Janelle Bynum (D-OR), Derek Tran (D-CA), and Steven Horsford (D-NV), and $512,000 each on Josh Gottheimer (D-NJ) and Pete Aguilar (D-CA). Most of the other endorsed candidates have so far received around $75,000 each from the network. Some of the biggest checks went to members who chair the committees with jurisdiction over crypto, including Hill (Financial Services) and Steil (digital assets subcommittee).
Conspicuously missing are several reliable crypto allies in tougher races, including Democrats Don Davis (NC) and Shomari Figures (AL) and Republicans Zach Nunn (IA) and Mike Lawler (NY). Fairshake spent more than $2 million each on Davis and Figures in 2024, and $1 million on Nunn; it didn’t back Lawler. Nunn and Lawler have, however, received smaller amounts of support this cycle from Andreessen Horowitz, one of Fairshake’s biggest backers, through donations by several executives to a crypto-themed joint fundraising committee called “Hodl the Line”.
Trump business interests
Trump has announced yet another $TRUMP memecoin “gala dinner” for November, following the inaugural event in May 2025 [I82, Guests] and a second one in April 2026 [I105]. Each has generated less excitement than the last: the memecoin price continues to erode; the previous pricey events offered little more than bragging rights, mediocre food, and subpar company; and the organizers continue to pare back access to Trump himself after drawing criticism over pay-for-access to the president. While these events are intended to juice the token’s price — which has already plummeted more than 95% from its highs — they have become increasingly ineffective, producing shorter and less dramatic price spikes.
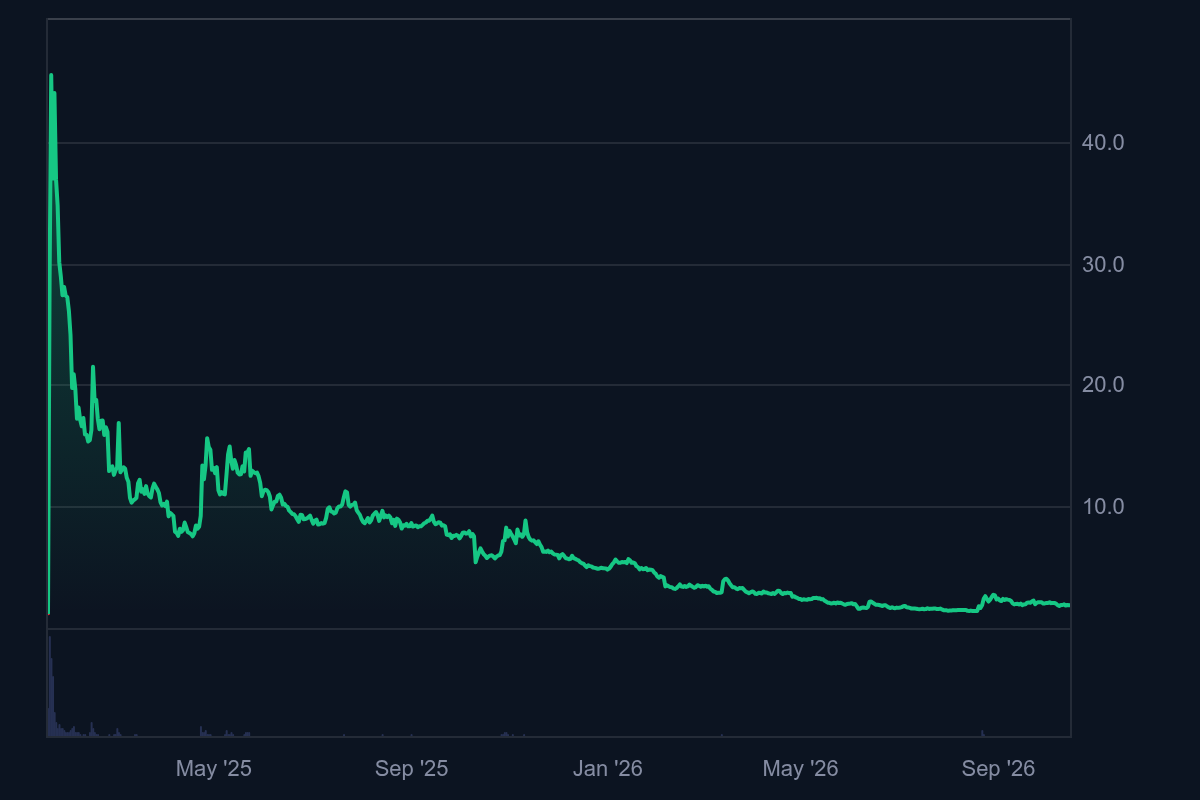
Kevin Mercuri, former spokesperson for Bill Zanker — who runs the $TRUMP memecoin and related portions of Trump’s personal business empire — criticized the event, calling the gala “tone-deaf” while “the nation is embroiled in a dead-end war and facing a widespread affordability crisis”.7 Trump personally pocketed more than $635 million from the memecoin during the 2025 fiscal year, as nearly all of the roughly one million retail traders lost money — a combined $3.8 billion.8 The fine print in the website now includes a disclaimer that the existence of events like the gala “does not indicate that Fight Fight Fight LLC, CIC Digital LLC or their respective affiliates are not contemporaneously disposing of $TRUMP coins”.9
The Trump memecoin website is also now teasing plans to invite the top 18 holders of the token to watch the Super Bowl from a “private luxury suite” and enjoy a “3-day VIP experience” including dinners and an “elite afterparty”. The fine print is careful to note that “President Donald J. Trump will not be in attendance in the Suite.” The plan is part of the “Trump Coin Club” membership scheme launched in April, which has so far held one event in which holders were invited to a Formula 1 race and “epic music festival” in Singapore [TCC].10
In the courts
Richard Heart
Richard Heart, the founder of the Hex cryptocurrency scheme, managed to spend nearly two years subject to an Interpol Red Notice before authorities finally nabbed him in Türkiye. The US SEC sued Heart in 2023, noting that asking people to “sacrifice” rather than “invest” their crypto assets in exchange for his PulseChain and Hex tokens was not the get-out-of-securities-laws-free card he seemed to think it was. The lawsuit further alleged he had misappropriated at least $12 million to buy sports cars, luxury watches, and the largest black diamond in the world [I35, 45, 73].11
Then, in September 2024, he was accused by Finnish authorities of evading several hundred million euros in taxes, and was named as a suspect in a brutal physical assault on a sixteen-year-old perpetrated in February 2021 [I67].12 At Finland’s request, Heart was added to the EU’s Most Wanted list and an Interpol Red Notice was issued [I72].
Turkish police have now arrested Heart and his wife in Istanbul. While a report from Turkish media outlet the Daily Sabah claims that Heart was wanted by Interpol on crypto fraud charges, the red notice only lists a charge of aggravated tax fraud.1314
Though Heart is certainly facing serious criminal consequences internationally, his US regulatory woes have eased. In February 2025, a federal judge dismissed the SEC’s lawsuit against Heart, finding the agency hadn’t adequately established that Heart had sufficient ties to the US. Heart thanked Trump for the outcome. Neither Trump nor his gutted SEC had anything to do with that ruling, but Heart may have had something to thank them for later on: in April 2025, the agency declined to amend its complaint to address the jurisdictional issues, effectively abandoning the case as it had so many others against crypto firms [I78, 82].
Everything else
A jury has convicted Jonathan Spalletta, the man who repeatedly exploited the Uranium Finance defi crypto exchange to steal more than $53 million [I78, W3IGG], which he then used to buy Magic: The Gathering and Pokémon cards, antique Roman coins, and a scrap of fabric from the original Wright brothers’ airplane that was later taken by Neil Armstrong to the surface of the moon. While Spalletta and his lawyers attempted the classic “code is law” defense, it probably did not help his case that the government was able to produce a message from Spalletta in which he wrote, “I did a crypto heist of $1.5MM a couple of weeks ago ... There was a bug in a smart contract, and I exploited it ... Crypto is all fake internet money anyway.”15
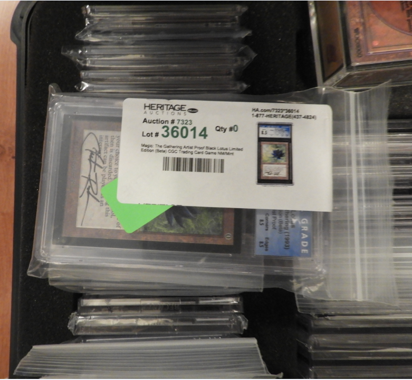
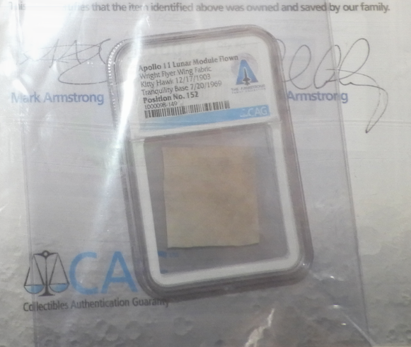
Spalletta used the proceeds of his crime to purchase a $500,000 “Black Lotus” Magic card and a $137,500 scrap of fabric from the original Wright brothers’ airplane that was later taken by Neil Armstrong to the surface of the moon (via the US Department of Justice)
In prediction markets
As New Jersey petitions the Supreme Court to take up the issue of whether state gambling laws should apply to prediction markets, it’s found a new ally in the National Football League. The NFL filed an amicus brief urging the Court to take up the case, arguing that sports contracts in prediction markets create new risk, rather than hedge existing risk, and therefore should be regulated by state gambling commissions. They detail complaints around Kalshi’s refusal to comply with their requests to ban bets that are easily manipulated, those involving injuries or referees, and those whose outcomes can be known in advance. They also note that Kalshi’s platform allows participants who are 18 or older, despite many state gambling laws that restrict betting to 21 and older.16
Unlike Major League Baseball and the National Hockey League, which have signed sponsorship or trademark deals with prediction markets, the NFL has been more hesitant. NFL games have drawn huge volumes on prediction markets, with the league’s games accounting for $1.8 billion of the $3.3 billion total prediction market volume on the first Sunday of the most recent NFL season. According to their brief, this is all the more reason for the NFL to worry about the emergence of such platforms, which they say undermine efforts to protect bettors, ensure wagers are fair, and limit threats to the integrity of the games themselves.16
Daniel Wallach, a gaming lawyer who focuses on sports betting, said that the NFL’s encouragement “meaningfully” increases the chances the Supreme Court will hear the case. He added, “It is extremely telling that the sports league which has most forcefully advocated for federal regulation is essentially saying ‘this ain’t it’.”17
The Web3 is Going Just Great recap
There were seven entries between September 30 and October 15. $86 million was added to the grift counter.
- Blur NFT marketplace to shut down [link]
- At least $86 million stolen via tampered Ledger hardware wallets resold by CryptoBilis [link]
- Pudgy Penguins company shuts down its Abstract blockchain after losing “8 figures” running it [link]
- Blur shuts down its Blast blockchain [link]
- Porsche shuts down its NFT project with the floor price down 96% [link]
- Near Intents exploited for $3.8 million, recovers all assets [link]
- Abracadabra proposes winding down after string of hacks years ago left each $1 “stablecoin” token backed by $0.04 in reserves [link]
That's all for now, folks. Until next time,
– Molly White
Have information? Send tips (no PR) to molly0xfff.07 on Signal or molly@mollywhite.net (PGP).
I have disclosures for my work and writing pertaining to cryptocurrencies.
References
Tweet thread by Harry Jung. ↩
“Trump names national intelligence chief Jay Clayton as new AI czar”, NPR. ↩
Letter from Senator Richard Blumenthal to Cantor Fitzgerald Chairman Brandon Lutnick, October 8, 2026. ↩
“Crypto megadonors play it safe in the House”, Politico. ↩
“Crypto super PAC to back candidates in 32 House races”, The Hill. ↩
“Trump’s Meme Coin Firm Wants You to Buy. Insiders Are Preparing to Sell.”, The Washington Sun. ↩
“Nearly a Million Investors Lost a Total of $3.8 Billion on Trump Crypto Coin”, The New York Times. ↩
2026–27 Winter Events Terms and Conditions, Trump Coin Club. ↩
Coin Club / Experiences / Super Bowl LXI, Trump Coin Club. ↩
Complaint filed July 31, 2023. Document #1 in SEC v. Schueler. ↩
“Finnish police suspect US crypto influencer of gross tax evasion and assault”, YLE News. ↩
“Türkiye nabs Interpol-wanted crypto fugitive in Istanbul operation”, Daily Sabah. ↩
“Jonathan Spalletta Convicted For Defrauding Crypto Exchange Of Over $50 Million In Hacks”, U.S. Attorney's Office, Southern District of New York. ↩
Brief of amicus curiae National Football League in support of petitioners, Flaherty v. KalshiEX, LLC. ↩
Footnotes
The implication that regulators can either grant the charter or watch Coinbase go ahead with its planned activities anyway is certainly bold, though it’s very much in keeping with the crypto industry’s general approach to regulation. ↩
Read more

Issue 110 – The Clarity Act collapses
Regulators race to reassure the crypto industry as the industry’s flagship legislation collapses, SBF tries his luck with the Supreme Court, and crypto PACs unleash $30 million against Sherrod Brown

The Senate must reject the Clarity Act’s ethics charade
The supposedly “unprecedented” ethics restrictions exempt Trump’s crypto businesses and leave enforcement to his loyalists

Issue 109 – Reg Crypto
The SEC’s “Reg Crypto” aims to carve out exemptions, the CFTC wields emergency powers to shield prediction markets from state regulators, and a Trump family crypto firm gets a bank charter

Issue 108 – In a word, applesauce
Firms close up shop amid a continued crypto winter, a Trump venture ditches its crypto plans, and the Clarity Act fails to reach a vote before August recess